November 2, 2026
When you find a luxury home you love in San Antonio, insurance may feel like a detail to handle after the inspections. I recommend bringing it into the conversation earlier. The goal is to understand the property and your ownership budget while there is time to compare options and ask follow-up questions.
A polished home can include custom finishes, several structures, a pool, and specialized equipment. An insurance conversation should reflect those details rather than treating every property as interchangeable.
Request property-specific insurance quotes early, compare the actual coverage and deductibles, and coordinate the final requirements with your insurance professional and lender.
As a Luxury Real Estate Advisor with Kuper Sotheby's International Realty, I help buyers organize the transaction. A licensed insurance professional should explain policy choices and determine the appropriate coverage for your situation.
Start With the Actual Property
Give the insurance professional the address and accurate available information about the home. Ask what documentation is needed, including details about construction, roof age, renovations, and the features you expect to use.
Identify detached structures, outdoor improvements, and equipment rather than assuming everything is treated the same way. If information is uncertain, say so and ask how to verify it. Guessing at a roof date or describing a partial renovation as a full replacement can create confusion.
A seller's existing premium can provide context, but it is not your quote. Your coverage selections and other underwriting information may differ. Obtain information for your proposed purchase and intended use.
Compare More Than the Annual Premium
A lower quoted premium deserves a closer look at what has changed. Put the coverage limits, deductibles, exclusions, and optional endorsements next to each other. Ask the insurance professional to explain material differences in plain language.
The Consumer Financial Protection Bureau recommends obtaining written quotes from several companies and reviewing them with the loan officer. Its guidance also notes that property characteristics and the cost to rebuild can influence pricing.
For a custom home, discuss the details that would matter in a repair or rebuilding scenario. Do not assume the purchase price or tax value answers every insurance valuation question. Ask how the proposed dwelling limit was developed and what assumptions it uses.
Understand Deductibles and Roof Coverage
Ask which deductibles apply to which events, how they are calculated, and what they mean in dollars under the proposed policy. If a quote uses a percentage deductible, ask what amount the percentage is applied to.
Roof terms deserve their own discussion. The Texas Department of Insurance's home insurance guide explains the distinction between replacement-cost and actual-cash-value coverage, with the latter accounting for depreciation. Ask which terms apply to the home and roof you are considering.
Do not make a coverage decision from a one-line summary alone. Request clarification about limitations, endorsements, or conditions that affect the protection you expect.
Discuss Water Risks Separately
Different kinds of water damage can involve different policy provisions. Ask about the proposed treatment of plumbing leaks, water backup, and flooding rather than grouping them together.
TDI explains that most home policies do not cover flood damage. Discuss whether separate flood coverage is appropriate and confirm any effective-date or waiting-period requirements with the insurance professional.
This conversation does not replace evaluation of drainage, property history, or inspection concerns. Treat physical due diligence and insurance review as related tasks with different purposes.
Explain How You Plan to Use the Home
Tell the insurance professional whether this will be your primary residence, a second home, or a property you expect to leave unoccupied for extended periods. If rental use or major work is contemplated, raise that before selecting coverage.
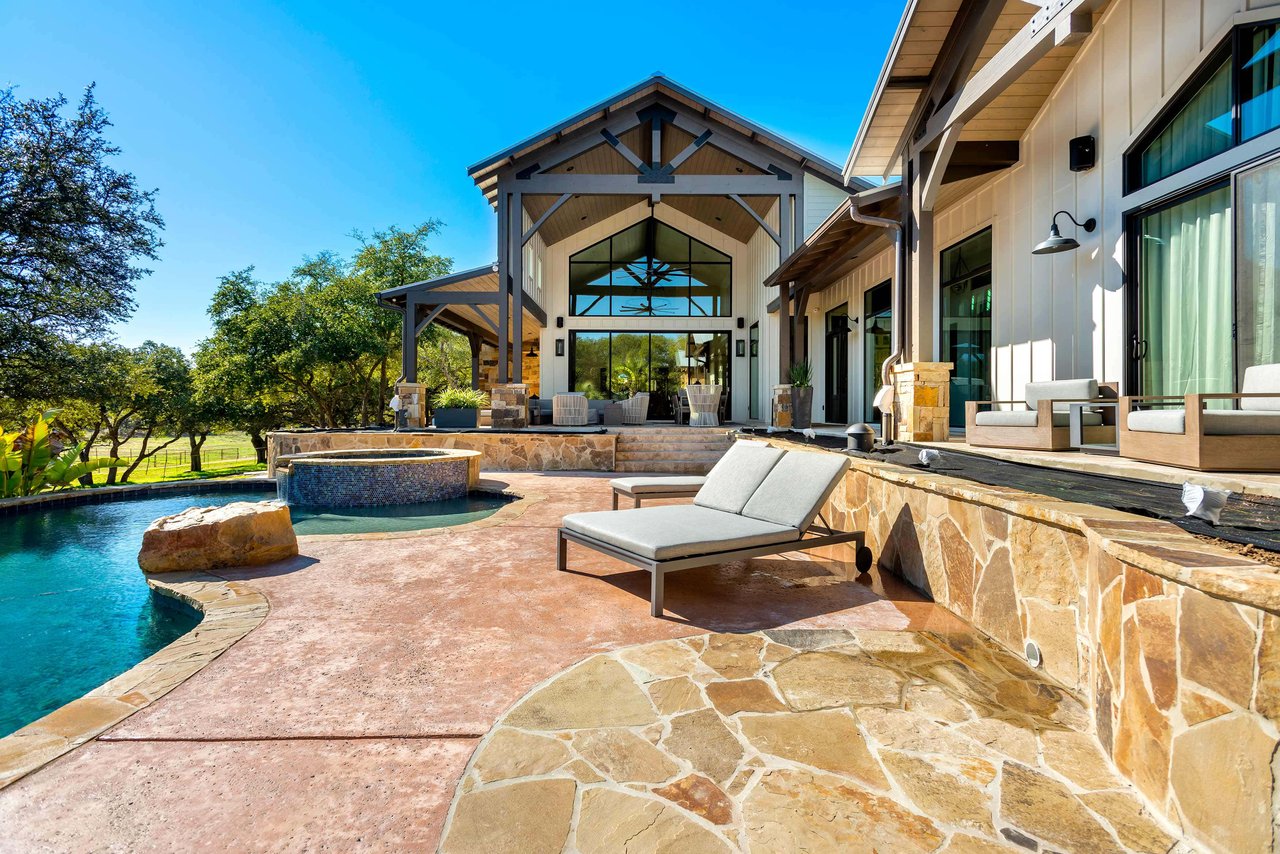
Also discuss features such as a pool, guest accommodations, and valuable personal property. Ask about the relevant liability and personal-property options. Avoid assuming that a standard limit covers every item or activity.
A useful quote reflects the way you intend to own and use the property. If those plans change, ask what needs to be updated.
Coordinate With the Closing Timeline
Ask your lender what evidence of coverage it needs and when. Confirm the proposed effective date, payment arrangements, and any outstanding underwriting requirements with the insurer.
Clarify whether the information in hand is an estimate, a quote subject to additional review, or confirmation that coverage has been bound. Do not assume that an emailed price alone completes the process.
Starting early creates room to resolve questions. It does not guarantee availability, a particular premium, or a right to change the purchase agreement. Raise any concern promptly with the transaction team and seek the appropriate professional advice.
Questions to Bring to the Insurance Conversation
- What property details or documents do you still need?
- How were the coverage limits determined?
- Which deductibles apply, and what would they mean in dollars?
- How are the roof and detached improvements treated?
- What water-related coverage is included or excluded?
- Does the policy match my intended occupancy and use?
- What must happen before coverage is confirmed for closing?
Frequently Asked Questions
Can I use the seller's insurance cost for my budget?
Use a quote prepared for you and the property. The seller's policy, coverage selections, and circumstances may be different.
Should I wait until all inspections are finished?
I recommend starting the conversation early and updating the insurance professional as reliable property information becomes available. Ask that professional what is needed to finalize the quote.
Plan the Ownership Details Alongside the Purchase
A thoughtful San Antonio luxury home purchase includes the experience of owning the property after closing. If you are preparing to buy, contact me to organize your search and the questions to address along the way.
Cody Miller | Luxury Real Estate Advisor | Kuper Sotheby's International Realty